
Navigating the world of taxes can feel overwhelming, especially when it comes to understanding how different types impact your financial future. Property tax, inheritance tax, estate tax, and gift tax are all examples of financial obligations that you need to consider. Each plays a unique role in wealth transfer and property ownership, potentially affecting your assets significantly.
Have you ever wondered how these taxes might influence your estate planning or gifting strategies? Understanding the nuances between these taxes is crucial for making informed decisions. In this article, we’ll explore each type of tax in detail and discuss their implications on your wealth. By grasping these concepts, you’ll be better equipped to navigate the complexities of taxation and safeguard your legacy for future generations.
Understanding Tax Types
Property tax, inheritance tax, estate tax, and gift tax represent key components of the taxation system. Each type plays a distinct role in financial planning.
Property tax is levied on real estate by local governments. You pay this annually based on your property’s assessed value. For example, if your home is valued at $300,000 with a property tax rate of 1.25%, you’ll owe $3,750 each year.
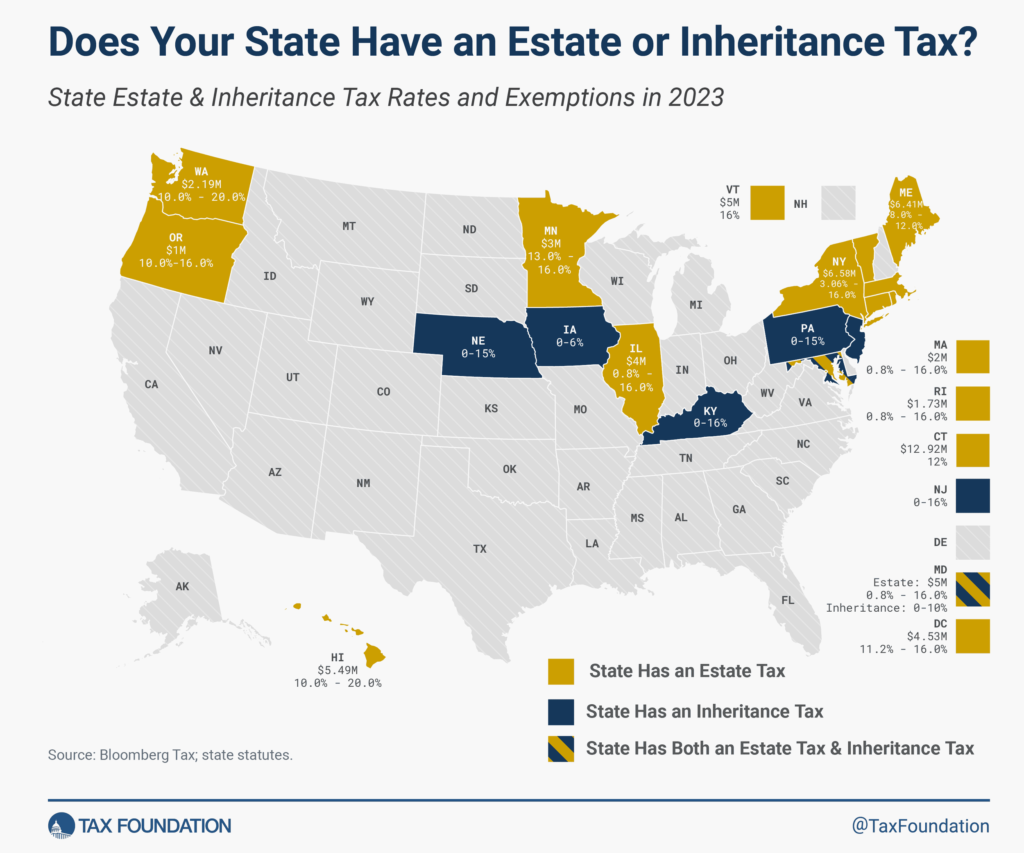
Inheritance tax applies to assets inherited from someone who has died. This varies by state; for instance, states like Maryland impose taxes that can reach as high as 10%. If you inherit $100,000 in Maryland, expect to pay up to $10,000.
Estate tax, on the other hand, concerns the total value of a deceased person’s estate before distribution to heirs. The federal threshold stands at $12.92 million for 2025; estates exceeding this amount face taxation rates starting at 18% and going up to 40%.
Gift tax affects monetary or asset transfers made during one’s lifetime without receiving something of equal value in return. Currently set at a threshold of $17,000 per recipient annually (as of 2025), any gifts above that amount may incur taxes.
Understanding these taxes helps you navigate financial responsibilities effectively and plan accordingly for wealth transfer strategies.
Property Tax
Property tax is a significant financial obligation for property owners. This tax is levied annually by local governments based on the assessed value of real estate. Understanding its implications helps in effective budgeting and financial planning.
Definition and Purpose
Property tax serves as a primary revenue source for local governments. This funding supports essential services such as education, public safety, infrastructure maintenance, and community programs. Additionally, it reflects the value of your property, ensuring that taxation aligns with market conditions.
How Property Tax is Calculated
Calculating property tax involves several key components:
- Assessed Value: Local authorities determine this value through regular assessments.
- Tax Rate: This rate varies by locality and often changes yearly; it’s expressed as a percentage or millage rate.
- Exemptions and Deductions: Homeowners may qualify for various exemptions (e.g., senior citizen or veteran status) that can reduce their taxable amount.
The formula generally looks like this:
Property Tax = Assessed Value × Tax Rate
For example, if your property’s assessed value is $300,000 and the local tax rate is 1.25%, your annual property tax amounts to $3,750. Understanding these calculations ensures you’re aware of your financial responsibilities related to property ownership.
Inheritance Tax
Inheritance tax represents a tax imposed on the assets you inherit from someone who has passed away. It’s important to understand that not all states apply this tax, and rates vary significantly where it exists.
Definition and Purpose
Inheritance tax is levied on the value of property or money inherited from a deceased individual. The purpose of this tax is to generate revenue for state governments while also addressing wealth distribution. If you’re an heir receiving assets, understanding your potential liabilities helps in effective financial planning.
Inheritance Tax Rates and Exemptions
Inheritance tax rates differ by state, often ranging from 1% to 16%. Some states provide exemptions based on relationship status. For instance:
- Direct heirs like children may enjoy higher exemptions.
- Distant relatives might face lower thresholds before taxation kicks in.
Additionally, certain estates may qualify for complete exemptions if they fall below specific asset values. Always check local laws since these figures can influence your inheritance significantly.
Estate Tax
Estate tax refers to a tax imposed on the transfer of property upon an individual’s death. This tax applies to the total value of the deceased person’s estate, including cash, real estate, stocks, and other assets. Understanding estate tax is crucial for effective financial planning.
Definition and Purpose
Estate tax serves as a way for governments to collect revenue from large estates. The purpose lies in ensuring that substantial wealth contributes to public funds. Generally, only estates exceeding a specific exemption threshold face taxation. For example, in 2025, the federal exemption amount stands at $12.92 million per individual.
Estate Tax Filing Process
Filing estate taxes involves several steps:
- Determine the Gross Estate Value: Calculate all assets owned by the deceased at the time of death.
- Identify Deductions: Recognize allowable deductions such as funeral expenses and debts.
- Complete IRS Form 706: Use this form for reporting estate tax information to the IRS.
- File within Nine Months: Submit your return within nine months after death or request an extension.
Gift Tax
Gift tax applies to the transfer of property or assets from one individual to another without receiving something of equal value in return. This tax aims to ensure that wealth distribution remains fair and prevents individuals from avoiding estate taxes through gifting strategies.
Definition and Purpose
Gift tax is imposed on transfers exceeding a certain value to prevent individuals from circumventing estate taxes. It targets large gifts made during a person’s lifetime. By taxing these transactions, governments maintain revenue flows while promoting equitable wealth distribution among citizens. You might wonder why this matters—it’s about fairness in how wealth gets passed down.
Gift Tax Exemptions and Limits
Understanding gift tax exemptions and limits helps you navigate potential liabilities efficiently. For 2025, the annual exclusion amount stands at $17,000 per recipient. This means you can gift up to this amount without incurring any gift tax. If you’re married, both spouses can combine their exclusions for joint gifts—effectively allowing you to give $34,000 annually to a single recipient.
Consider these key points regarding gift tax:
- Lifetime Exemption: The lifetime exemption limit for 2025 is approximately $12.92 million.
- Gifts Not Subject to Tax: Certain transfers like tuition payments or medical expenses paid directly are not subject to gift tax.
- Taxable Gifts: Any amount exceeding the annual exclusion counts as a taxable gift, requiring filing IRS Form 709.
With careful planning around these limits, you can minimize your overall tax exposure while making meaningful gifts.
Connection Between Taxes
Property tax, inheritance tax, estate tax, and gift tax are all examples of taxes that impact financial planning. Understanding how these taxes connect is vital for effective wealth management.
Property tax serves as a recurring expense. Local governments assess the value of a property annually to determine the amount owed. You might find your property taxed at 1.25% of its assessed value, leading to significant annual costs based on real estate market fluctuations.
Inheritance tax varies by state and directly affects heirs. Some states impose this tax on assets received from deceased individuals, with rates ranging from 1% to 16%. If you inherit from a distant relative, expect lower exemptions compared to direct heirs like children.
Estate tax, unlike inheritance tax, applies before asset distribution occurs. It targets the total value of an individual’s estate once they pass away. For instance, in 2025, estates exceeding $12.92 million face federal taxation—defining which assets contribute to overall wealth transfer burdens.
Gift tax prevents avoidance of these other taxes through lifetime gifting strategies. It applies when you transfer assets without receiving equal value in return. In 2025, you can give up to $17,000 per recipient annually without triggering this tax; married couples can double this limit for joint gifts.
These taxes create a web affecting each other and your financial decisions. By navigating them effectively, you protect your legacy while ensuring compliance with regulations governing wealth distribution.