
Have you ever wondered why predatory lenders get their negative reputation from? These financial entities often target vulnerable individuals, offering seemingly attractive loans that come with hidden traps. Their tactics can lead to overwhelming debt and financial distress, leaving borrowers feeling trapped.
In this article, we’ll explore the key factors contributing to the notorious image of predatory lenders. From exorbitant interest rates to deceptive practices, you’ll discover how these lenders exploit desperation and lack of knowledge. Understanding these elements not only sheds light on their bad reputation but also empowers you to make informed decisions when seeking financial assistance. Stay tuned as we unravel the complexities behind predatory lending and help you navigate away from potential pitfalls.
Overview of Predatory Lenders
Predatory lenders exploit vulnerable individuals through deceptive and harmful lending practices. They often target those in desperate financial situations, offering seemingly attractive loans that mask hidden fees and excessive interest rates.
High-interest rates represent one of the most significant indicators of predatory lending. These rates can exceed 400% in some cases, trapping borrowers in a cycle of debt.
Deceptive terms also play a crucial role in this negative reputation. Many lenders promote loans with low initial payments but fail to disclose the total cost over time, leading to unexpected financial burdens.
Lack of transparency is another red flag. Borrowers may receive little information about loan conditions or repayment schedules, making it difficult to make informed decisions.
Aggressive collection practices further tarnish the image of predatory lenders. Some use harassment tactics or threaten legal action, creating additional stress for already struggling borrowers.
By understanding these examples, you can better navigate the lending landscape and avoid falling victim to predatory lenders’ traps.
Factors Contributing to Negative Reputation
Predatory lenders face significant scrutiny due to several key factors that shape their negative reputation. These elements not only affect borrowers’ experiences but also contribute to the overall distrust surrounding these lending practices.
High-Interest Rates
High-interest rates play a major role in the negative perception of predatory lenders. Many loans come with interest rates exceeding 400%, which leads to overwhelming debt for borrowers. For instance, if you borrow $1,000 at such a rate, you could end up repaying over $5,000 within a year. This staggering cost can trap individuals in cycles of debt that are hard to escape.
Deceptive Practices
Deceptive practices further tarnish the image of predatory lenders. They often advertise low initial payments without clearly disclosing the total cost or hidden fees associated with loans. Borrowers might think they’re getting a good deal until they realize additional charges inflate their obligations significantly. For example, an advertised loan might seem affordable at first glance but can include penalties for late payments and ballooning interest rates that catch borrowers off guard.
Targeting Vulnerable Populations
Targeting vulnerable populations is another critical factor contributing to the negative reputation of predatory lenders. These lenders frequently approach individuals facing financial difficulties, such as those with poor credit or unexpected medical bills. By exploiting desperation, they offer loans that appear beneficial but ultimately lead to greater hardship. Communities affected by economic instability often see numerous advertisements for high-risk loans aimed specifically at those who may lack access to traditional banking options.
Impact on Borrowers
Predatory lending significantly impacts borrowers, leading to severe financial and emotional repercussions. Understanding these consequences helps you avoid falling victim to such lenders.
Financial Consequences
High-interest rates burden borrowers with payments that can exceed their original loan amounts. For instance, a loan of $1,000 at a 400% interest rate can result in repayments totaling over $4,000 within one year. Hidden fees often accompany these loans, further escalating costs without clear disclosure from the lender. Some common financial pitfalls include:
- Loan terms: Unclear repayment schedules create confusion.
- Debt cycles: Many borrowers find themselves trapped in continuous loans due to mounting debt.
- Asset loss: Failure to repay can lead to repossession of collateralized assets.
These factors contribute heavily to the overall negative reputation of predatory lending practices.
Emotional Stress
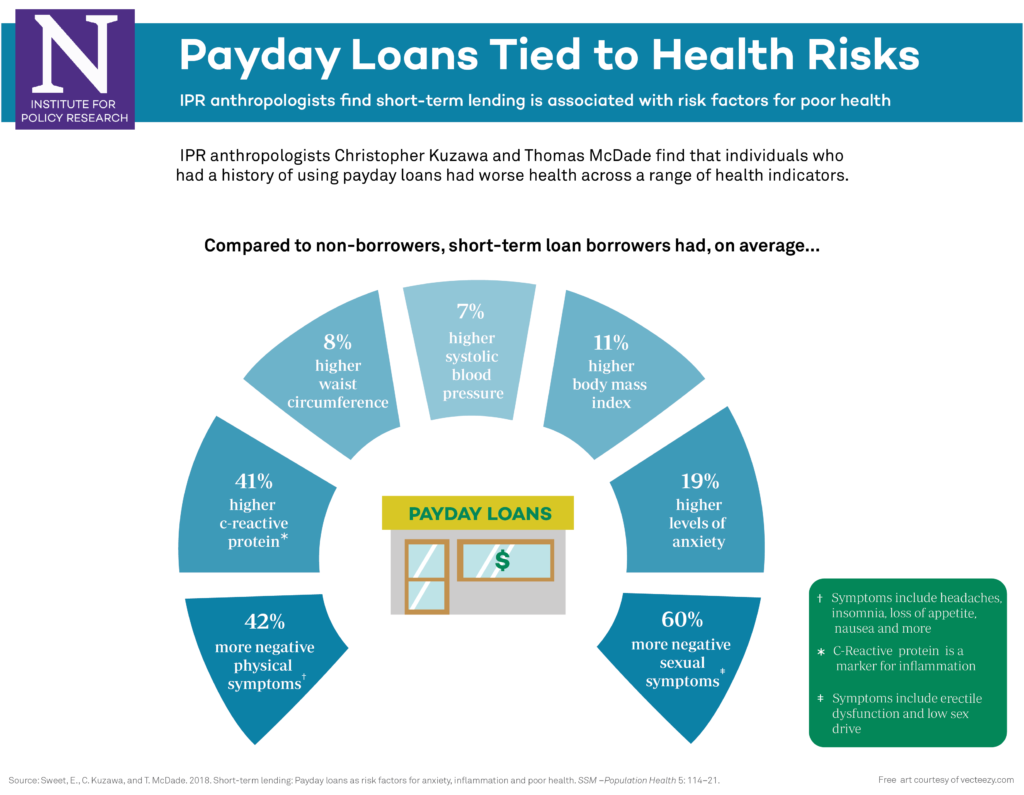
The experience of dealing with predatory lenders causes significant emotional stress for many individuals. The constant worry about finances can lead to anxiety and depression. Consider how aggressive collection tactics affect mental well-being:
- Harassment: Frequent calls or messages create feelings of helplessness.
- Legal threats: The fear of legal action adds pressure and uncertainty.
- Isolation: Borrowers may withdraw socially due to embarrassment over their financial situation.
Such emotional burdens reinforce the perception that predatory lending is not just a financial issue but also a deeply personal struggle for many victims.
Regulatory Responses
Regulatory responses play a crucial role in addressing the issues associated with predatory lending. Various measures aim to protect consumers and ensure fair lending practices.
Government Interventions
Government interventions include legislation and regulatory bodies that oversee lending practices. For example, the Truth in Lending Act (TILA) requires lenders to provide clear information about loan terms and costs. This transparency helps you understand what you’re signing up for before committing to a loan.
Another significant measure is the Dodd-Frank Wall Street Reform and Consumer Protection Act, which established the Consumer Financial Protection Bureau (CFPB). The CFPB monitors financial institutions, ensuring they comply with consumer protection laws. Additionally, it offers resources for borrowers who feel exploited by predatory lenders.
State-level regulations also exist. Some states have implemented strict interest rate caps on payday loans, limiting how much lenders can charge borrowers. These caps prevent consumers from falling into cycles of debt due to exorbitant fees.
Furthermore, many jurisdictions enact anti-harassment laws that prohibit aggressive collection tactics by lenders. Such protections empower you against unlawful pressure and threats.
Overall, these government interventions aim to create a safer lending environment while holding predatory lenders accountable for their actions. By understanding these regulations, you can better navigate your borrowing options and avoid potential pitfalls associated with unscrupulous lending practices.