
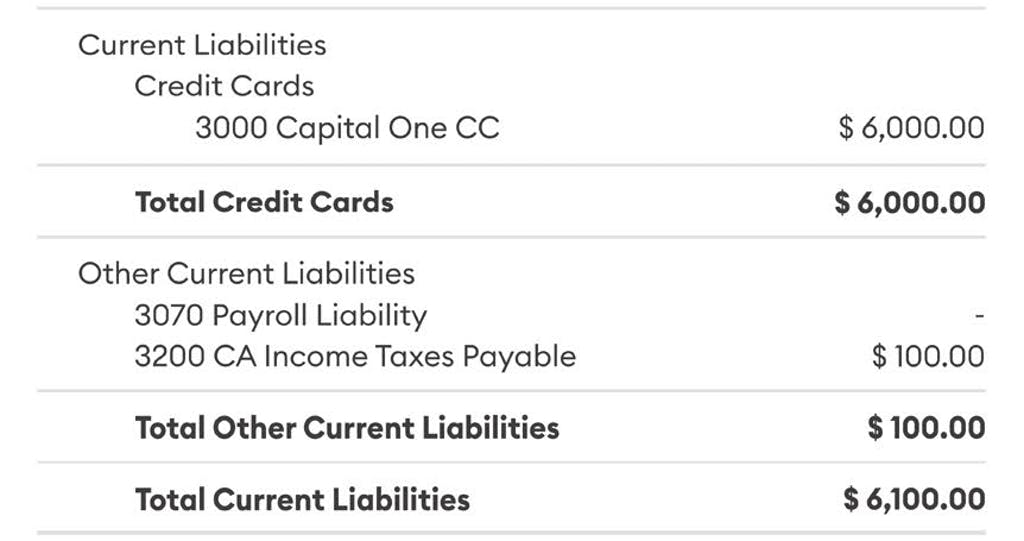
Managing your finances can feel overwhelming, especially when you’re juggling multiple obligations. Medical bills, credit card balances, and home equity loans are all examples of current liabilities that can impact your financial health. Understanding these liabilities is crucial for effective budgeting and long-term planning.
Understanding Current Liabilities
Current liabilities represent obligations that you must settle within one year. These include various types of debts, and understanding them is crucial for effective financial management.
Medical bills can accumulate quickly. If you receive unexpected healthcare services, these costs may lead to immediate financial strain. Keeping track of these bills helps avoid late fees or potential impacts on your credit score.
Credit card balances also fall under current liabilities. When you use a credit card, you’re borrowing money that needs repayment. High-interest rates can turn manageable balances into significant debt if not paid off promptly.
Home equity loans, while often used for major expenses, become current liabilities once borrowed funds are due for repayment. You leverage your home’s value but remember: failure to repay can threaten your property.
By recognizing these examples of current liabilities, you enhance your budgeting efforts and prepare better for future financial decisions.
Types of Current Liabilities
Current liabilities encompass various obligations that require settlement within one year. Understanding different types helps you manage your finances more effectively.
Medical Bills
Medical bills represent a significant current liability for many individuals. These expenses can arise unexpectedly from hospital visits, surgeries, or treatments. You might encounter charges from multiple providers, including doctors, specialists, and labs. It’s essential to track these bills closely to avoid late payments and potential negative impacts on your credit score.
Credit Card Balances
Credit card balances can quickly become overwhelming current liabilities. High-interest rates often accompany unpaid balances, leading to increased debt over time. When managing credit cards, pay attention to due dates and minimum payment requirements. It’s wise to prioritize paying off higher interest cards first to reduce overall financial strain.
Home Equity Loans
Home equity loans turn into current liabilities once repayment begins. These loans allow you to borrow against your home’s value but come with specific repayment terms. If you’re using a home equity loan for renovations or consolidating debt, ensure you understand the payment schedule and interest rates involved. Staying informed about these aspects helps maintain financial stability while utilizing this resource effectively.
Impact on Financial Health
Understanding the impact of current liabilities like medical bills, credit card balances, and home equity loans is crucial for maintaining financial health. These obligations can significantly affect your overall financial stability and decision-making process.
Debt-to-Income Ratio
Your debt-to-income ratio (DTI) measures how much of your income goes toward debt payments. A high DTI indicates a greater financial burden, often limiting future borrowing options. For example:
- If your monthly income is $5,000 and your total debt payments are $2,000, your DTI is 40%.
- Lenders typically prefer a DTI below 36% for favorable loan terms.
Managing current liabilities helps keep this ratio in check, allowing you to pursue loans or mortgages more easily.
Credit Score Considerations
Current liabilities also influence your credit score. Timely payments on medical bills and credit card balances boost your score; late payments hurt it. Here are key points to consider:
- Payment history accounts for about 35% of your credit score.
- High credit utilization from maxed-out cards can lower your score significantly.
Staying aware of these factors allows you to make informed decisions that protect and enhance your creditworthiness.
Strategies for Managing Current Liabilities
Managing current liabilities effectively ensures financial stability and reduces stress. Here are some strategies to help you tackle these obligations.
Budgeting Techniques
Implementing effective budgeting techniques helps track and manage your current liabilities. Start by categorizing your expenses into fixed and variable costs. This can provide clarity on where your money goes each month.
- Create a monthly budget: List all income sources along with fixed expenses like rent, medical bills, and credit card payments.
- Use budgeting apps: Consider utilizing apps that simplify tracking spending habits and remind you of upcoming due dates.
- Prioritize payments: Focus on high-interest debts first, as they accumulate faster than lower-interest ones.
Consolidation Options
Consolidating various debts can simplify repayment processes while potentially lowering interest rates. Explore these options if you’re juggling multiple current liabilities:
- Debt consolidation loans: These loans combine several debts into one monthly payment at a lower interest rate.
- Balance transfer credit cards: Transfer balances from high-interest cards to a card with a promotional 0% APR for an introductory period.
- Home equity loans: If you have substantial equity in your home, this option allows you to borrow funds at lower interest rates—be cautious about using your home as collateral.
By employing these strategies, you’re better positioned to manage current liabilities efficiently while maintaining overall financial health.